01Verify and prepare
Enable only selected lawful access
Complete approved client onboarding, segment permissions and account links. Publish admitted instruments with current trading rules and licensed market information.
Brokerage and market access
Low-friction brokerage portal for eligible cash-market and approved investment products. Planned for licensed brokers serving self-directed investors with education and risk controls with role-specific workflows, operator controls, integrations, and a handover boundary defined for the selected market.
Professional plan. Enterprise customization is quoted on scope.
Custom workflows
Brand-safe product strategy
Admin and operations tooling
Reference walkthrough by arrangement
Workflow
Each workflow stage is mapped to a role, screen, API, notification, admin control, and measurable launch outcome.
Complete approved client onboarding, segment permissions and account links. Publish admitted instruments with current trading rules and licensed market information.
Check funds, eligibility and instrument constraints before routing. Retain broker and venue identifiers with accepted, rejected, partially filled and pending cancellation states.
Reconcile executions, cash, margins and settlement records. Deliver reviewed contract notes and holdings information with correction and grievance routes.
Deployable Product Architecture
Workflow / system register
Product delivery loop
Zerodha-style Self-directed Brokerage workflow stages.
A focused release proves one complete workflow
Enable only selected lawful access
Separate order submission from execution
Explain what the client owns and owes
Control note
Scope the customer action and the operator response as one system.
Operator controls
The control center is scoped as a first-class product surface, not an afterthought.
Validate account status, approved products and current restrictions at submission. Authentication alone cannot establish permission for every instrument or exchange segment.
Revalidate stale values and available resources on the server. An indicative buying-power figure does not guarantee order acceptance or waive broker risk checks.
Separate client cash, pending settlement and holdings records. Reconcile differences through restricted corrections without overwriting the trade history or implying protection the arrangement does not provide.
Integrations
External systems that determine launch readiness, data flow, and operational continuity.
Selected authorized brokerage, order management and risk systems with scoped account permissions and traceable venue identifiers
Permitted exchange data, instrument masters and trading calendars with freshness, entitlement and restriction checks
Approved clearing, depository, banking, client-ledger and reporting services with reconciled statements and restricted grievance records
Scope drivers
The variables that most influence build effort, cost, and launch readiness.
Choose eligible accounts, exchanges and cash instruments. Each added segment introduces reviewed access, market-data, risk and reporting responsibilities.
Define peak order load, venue responses and cancel or modify behavior. Rehearse missing acknowledgements and replay reconciliation before broadening order types.
Scope holdings, margins, contract notes, corporate actions and correction cases. A trading screen does not remove clearing, depository or support responsibilities.
Deployable Product Architecture
Scope drivers / system register
Product delivery loop
Zerodha-style Self-directed Brokerage scope drivers.
A focused release proves one complete workflow
Count permissions and operating rules
Specify unresolved instruction handling
Staff the records after execution
Control note
Scope the customer action and the operator response as one system.
V1 scope
Launch the smallest complete operating loop first, then scale the product with confidence.
Provide synthetic onboarding, selected instruments and entitled quotes. Demonstrate an unauthorized segment and a stale quote with an explicit customer explanation.
Support selected order types with rejections, partial fills and pending cancellation. Retain request identifiers and reconcile a cancel race without duplicate orders.
Provide funds, margin information, holdings and reviewed contract-note records. Rehearse a settlement difference, corporate action and attributable correction case.
Later phases
Capabilities that should usually wait until real usage proves the core loop.
Add products only after confirming permissions, disclosures, risk rules and servicing. Derivatives and leveraged facilities need a separate scope beyond cash-market v1.
Add approved exports and action-specific servicing after validating identifiers, entitlement dates and correction ownership. Informational reports do not become personalized advice.
Add reviewed connectivity redundancy and operational tooling while retaining order identity and client segregation. Measure capacity using actual contracted dependencies.
Deployable Product Architecture
Later phases / system register
Product delivery loop
Zerodha-style Self-directed Brokerage post-launch expansion.
A focused release proves one complete workflow
Expand through separate product review
Extend reconciled account evidence
Scale demonstrated recovery paths
Control note
Scope the customer action and the operator response as one system.
Regulatory review
Each flag must be reviewed by qualified counsel for your target market before build or launch.
Reference walkthrough
Ask us to confirm which reference surfaces are currently available for this product model. Rather than publishing shared demo credentials, we schedule a private guided walkthrough for qualified buyers.
Request a role-specific demonstration and confirm which capabilities are currently available. Review the proposed responsibility: Review selected instruments, place bounded orders and inspect executions, positions, holdings and notes. Informational screens must not imply personalized investment advice.
Request a role-specific demonstration and confirm which capabilities are currently available. Review the proposed responsibility: Validate entitlements, route permitted instructions and reconcile broker, exchange, clearing and depository records. A client interface does not confer exchange membership.
Request a role-specific demonstration and confirm which capabilities are currently available. Review the proposed responsibility: Review rejected orders, margin differences and disputed statements. Restrict adjustments and preserve original records alongside corrections and customer explanations.
Request a live, private walkthrough of the reference implementation. We will confirm scope and discuss configured deployment versus custom build for your market.
Open registerDeployable Product Architecture
Reference walkthrough / system register
Product delivery loop
Request a Zerodha-style Self-directed Brokerage reference walkthrough.
A focused release proves one complete workflow
Eligible self-directed investor: Understand instructions and account records
Authorized broker operations: Own execution access and client reconciliation
Risk, reporting and grievance reviewers: Investigate exceptions with attributable decisions
Book a walkthrough
Control note
Scope the customer action and the operator response as one system.
User roles
Clone-inspired platforms usually need several coordinated interfaces, not just a customer app.
Review selected instruments, place bounded orders and inspect executions, positions, holdings and notes. Informational screens must not imply personalized investment advice.
Validate entitlements, route permitted instructions and reconcile broker, exchange, clearing and depository records. A client interface does not confer exchange membership.
Review rejected orders, margin differences and disputed statements. Restrict adjustments and preserve original records alongside corrections and customer explanations.
Live demo
Open each app or panel in a new tab and sign in with the demo login shown. The demos run on shared sample data, carry our demo product names, and show the ready-made product before any customization.
Trader Web App
trader@mxzodha.com | Demo@123Investor Portal
investor@mxzodha.com | Demo@123Broker Back Office
admin@mxzodha.com | Demo@123Android App
demo@mxzodha.com | Demo@123Use this trading-preferences reference to discuss alerts and client settings, then request a working Zerodha-style demo with sample quotes, rejected instructions and position differences. Agree the broker, market-data and software responsibilities for the proposed instruments and accounts, and identify simulated records and provider dependencies.
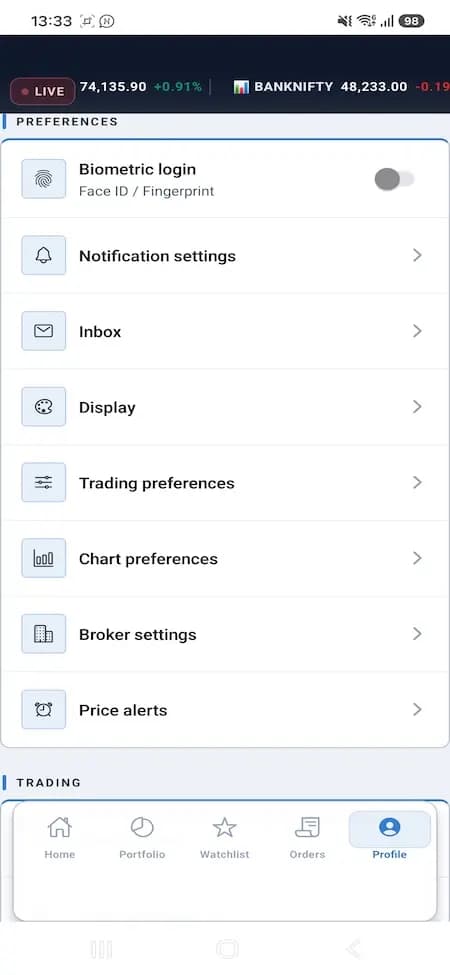
Illustrative trading-preferences reference at 450×975 with a biometric-login toggle, notification settings, broker settings and price alerts. Index values and the LIVE label are sample interface content; they do not demonstrate a connected data feed or order execution. Request a working Zerodha-style demo for data permissions, rejected orders and position reconciliation. This reference does not establish broker authorization, tested security or affiliation with Zerodha.
What to check in the walkthrough
Product flow
A visual map of how each role interacts with each workflow stage, with operator controls and integration boundaries.
Deployable product architecture
Zerodha-style Self-directed Brokerage
Workflow
Roles in the loop
Operator controls
Integrations underneath
Monetization
We model monetization early so payments, admin controls, and reporting support the business.
Describe brokerage and applicable charges for the selected activity. Distinguish estimates from finalized charges and avoid claims of guaranteed savings or returns.
Price supported account administration or reporting where permitted. Paid access cannot bypass eligibility, risk checks or investor grievance handling.
Define feed scope, freshness and permitted client access. The brand comparison does not supply exchange data rights or access to any reference provider.
Artifact register
Reference screens illustrate workflows, not a contracted feature list. Sample prices, data, and responses are demonstration content; confirm the current scope during a walkthrough.
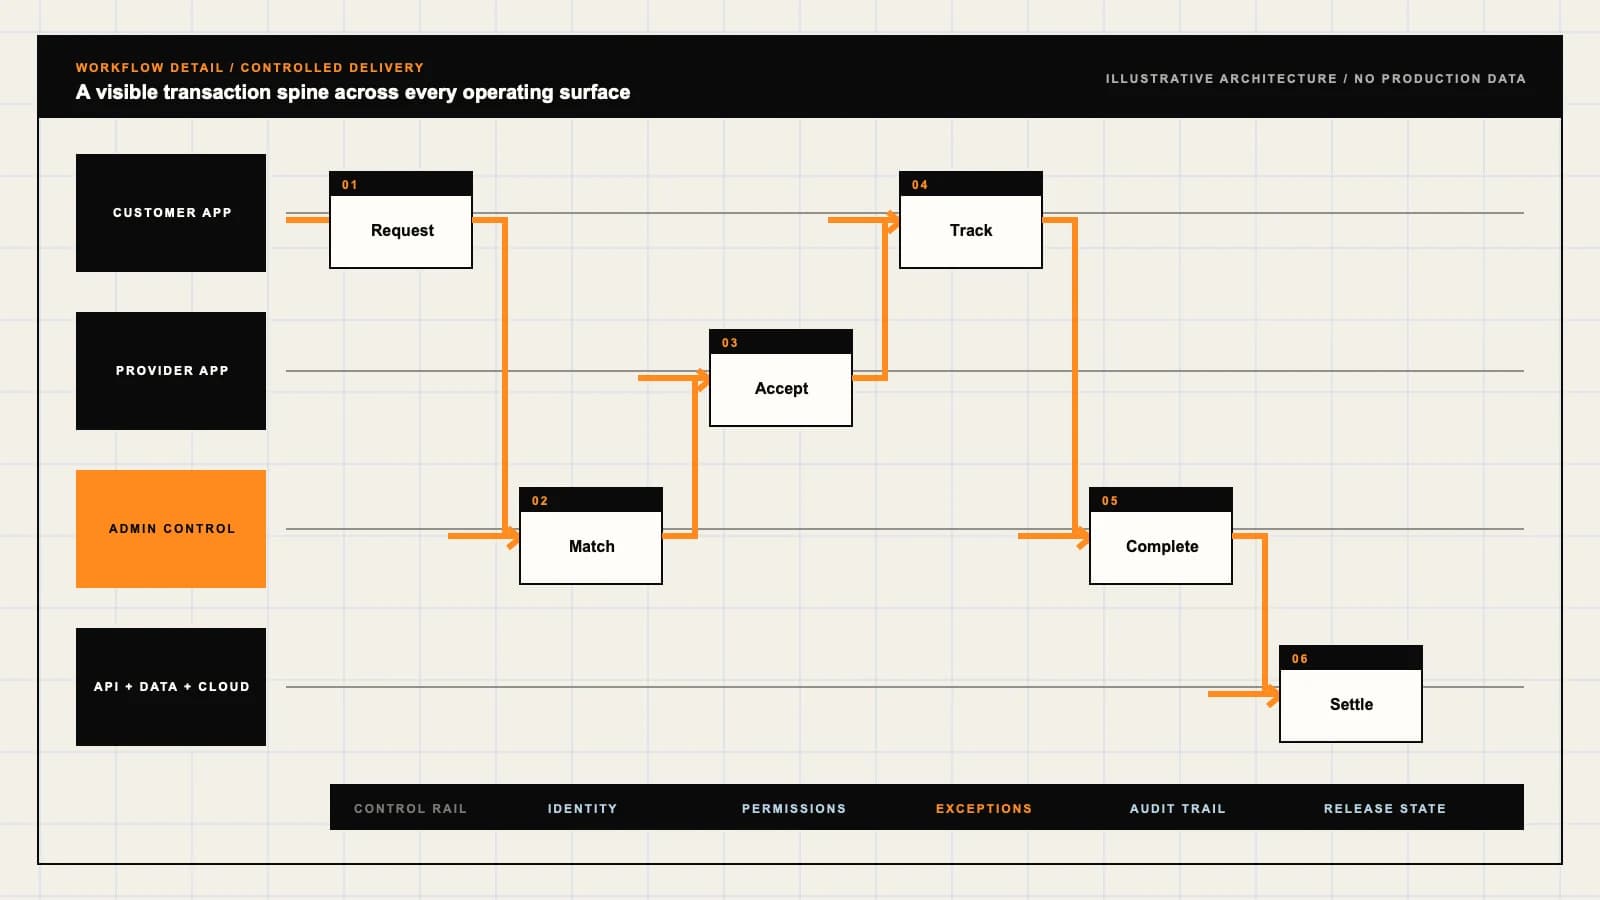
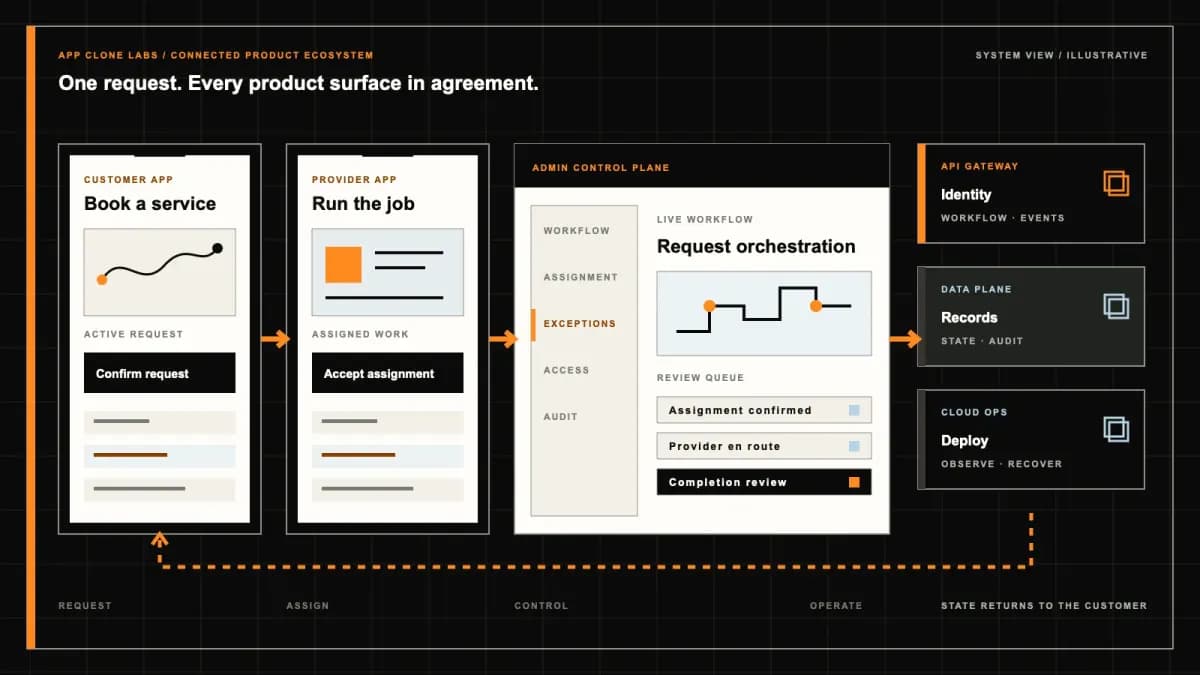
A fictional investor, Kavya, submits an order for ten shares of fictional company NILA. Four shares execute before she requests cancellation; another share executes while the cancellation travels to the venue. Her workspace must show five completed shares, the remaining canceled quantity and the cash obligation. It must also explain why an executed purchase is not yet the same record as a settled holding. That account story is the core of a Zerodha-style brokerage brief.
App Clone Labs scopes independently branded client software for India-oriented securities brokerage around selected lawful access and reconciled records. This reference does not imply Zerodha affiliation, exchange membership, provider access or operating permission. No investment advice or trading returns are promised. The operator must establish its own authorized brokerage, clearing, depository and data arrangements before enabling live client activity.
Define the responsible broker, client identity checks, account links and selected cash-market permissions before presenting an actionable trading workspace. An application received is different from a client approved to trade. Keep incomplete verification, pending account activation and rejected applications understandable, with a support route that does not invite users to bypass the missing requirement through another account.
Make exchange and product entitlements explicit under the actual arrangement. A signed-in customer may still lack permission for a segment, instrument or transaction type. Revalidate those permissions at the consequential step rather than relying on a screen opened earlier. Rehearse a client restriction arriving between instrument discovery and submission. Preserve the attempted instruction and reason safely, while preventing execution. Brokerage authorization and market access require qualified review; building account-opening screens cannot supply either.
Bind each selectable security to the appropriate instrument identifier, exchange, trading series and current rules. A familiar company name does not establish the intended listing. Show the source and timestamp of market information with the permissions required by the data contract. A last traded price is historical evidence, not a promise that a new order can execute at that value.
Handle suspended instruments, changed symbols and stale quotes before the customer submits. Test NILA appearing on two fictional venues while only one route is approved. Then stop the selected feed while the client leaves the order ticket open. The interface should explain the stale quote and apply the agreed submission policy. Instrument master changes must preserve historical order identity. A renamed security should not make an earlier execution appear to refer to a different asset.
Specify the supported cash-market order types, quantity increments, price rules, market session and client permissions. Validate exact amounts and current broker risk decisions on submission. Treat a displayed funds figure or earlier margin estimate as information that can change, particularly when another instruction has already reserved resources. Explain a rejected order in language that helps the client understand the failing condition.
Rehearse insufficient available funds, a changed instrument rule and an attempt outside the permitted session. Do not silently alter the requested quantity or product to make validation pass. Keep the customer’s instruction, the applied checks and the resulting reason attributable. An estimated charge is different from a final execution charge. Define which values are indicative and which govern acceptance under the selected broker contract, including what happens if a request arrives from an older screen or connected client.
The official Kite Connect order documentation explains that successful API placement does not imply successful execution and describes separate order history and trade records. This supports the distinction between an acknowledged instruction and a completed trade; it does not establish access to that API for an independent product.
Keep submitted, broker accepted, venue acknowledged, rejected, open and executed states distinct where supported by the chosen interface. Retain client request, broker order and exchange identifiers without assuming they arrive together. Test a placement timeout after the broker has accepted the instruction. Establish its existing outcome before retrying, so a connection failure cannot create two customer orders. Show uncertainty honestly and assign investigation when the authoritative result remains unavailable.
Kavya’s ten-share order has separate requested, filled, pending and canceled quantities. Every fill needs its own execution identity, quantity and price. A cancellation request affects the remainder if accepted; it cannot undo an execution that already occurred. Show pending cancellation while the venue decision is unresolved and preserve the final sequence when the customer reconnects.
Rehearse the fifth share executing during cancellation, duplicate fill events arriving and a delayed cancellation acknowledgement. The final record should account for the entire requested quantity once, with the associated cash and fees based on actual executions. A user pressing cancel is not proof that nothing traded. Modification needs the same care: distinguish a requested change from accepted replacement terms and explain any restriction affecting the remaining quantity. Support should be able to reconstruct the sequence without editing the history.
Kite Connect’s official portfolio documentation provides distinct positions and holdings records, including fields for unsettled quantities. Those interfaces are a reference for separating trading activity from account inventory, not a universal settlement promise or proof that the proposed operator has depository connectivity.
Explain today’s executed position, pending settlement and settled holding under the actual broker and depository records. Do not duplicate ownership by adding every visible quantity together. Kavya’s five executed shares should remain traceable as their reporting category changes. Rehearse a delayed holdings update and a sale instruction against quantities that are not currently available under the selected rules. Preserve the restriction explanation without inventing a guaranteed settlement date or assuming every instrument follows identical handling.
Separate cash credited, funds available for the permitted activity, amounts reserved and obligations awaiting final posting. Explain the timestamp and source of margin information. A displayed balance can differ from buying power or withdrawable funds, and the client needs the reason before taking another action. Keep provisional calculations visibly distinct from finalized broker ledger entries.
Rehearse a fill consuming a reservation, a rejected order releasing it and a delayed bank update. Reconcile these events without counting a reservation release as new income. Margin differences should create an attributable exception with a named owner and current evidence. Keep cash-market v1 separate from leveraged facilities and derivatives; those products require additional reviewed permission and risk decisions. Neither a green balance badge nor a successful synthetic order proves that real funds are available or that credit will be extended.
Scope contract notes and account statements as client records with controlled generation, delivery and retrieval. Connect the reported executions, quantities, prices and applicable charges to their source records. An order confirmation is not a substitute for a reviewed contract note. Distinguish estimates shown during order entry from finalized amounts and explain when a report remains under preparation or correction.
Use the operator’s applicable obligations and approved reporting arrangements to define formats, delivery timing and retention; avoid copying an assumed universal schedule into the interface. Test a partially filled order appearing across the correct executions, an unavailable document and a delivery failure. A corrected note should retain version history and a reason, rather than silently replacing the record the customer downloaded. Restrict document access to the relevant client and authorized staff, including during support-assisted investigation.
Agree how the client raises a grievance about a missing execution or unexpected charge. Connect the case to the relevant note and underlying events, with acknowledgment, ownership and escalation under the broker’s reviewed process. Operations should retain enough evidence to explain the discrepancy across customer support and reporting teams. A downloadable document with correct formatting is not sufficient acceptance evidence when its quantities or charges cannot be traced to the reconciled account records.
A split, bonus issue, dividend or other corporate action can change how a client interprets quantity, cost and cash records. Define the authoritative source, relevant entitlement information and posting status for the selected action. A market price changing does not prove that the corresponding holdings adjustment has been received or reconciled. Show pending information without manufacturing an entitlement or promising an outcome.
Rehearse fictional NILA announcing a split while the depository update arrives later than the market-data change. Compare source records, preserve the original trade identity and explain any temporary difference. Reconciliation should connect exchange executions, broker cash, clearing obligations and holdings records, with exceptions assigned to accountable teams. Restrict corrective adjustments and preserve supporting evidence. A support agent should investigate a disagreement through that trail, not overwrite average cost or quantity until the account screen looks plausible.
Compare the Blueberry Markets-style broker portal when the buying problem concerns platform access and leveraged-market account servicing. This India-oriented cash-market brief instead centers on selected securities permissions, order evidence, holdings, contract notes and broker reconciliation.
Review the white-label trading platform for a broader branded workspace decision. Here, keep v1 bounded to approved cash instruments and the agreed broker interfaces. Price permitted brokerage, account services and authorized data with clear disclosures. Paid features cannot bypass risk decisions or imply superior investment outcomes. Education and factual account information should remain separate from personalized recommendations; any advisory or research offering needs its own qualified review and authorized scope.
Use illustrative screens alongside a synthetic sandbox walkthrough with Kavya, NILA and controlled broker records. Buyer acceptance should demonstrate a stale quote, rejected order, partial fill and cancel race. Inspect the five-share execution result, pending settlement, position versus settled holding, margin changes and contract-note charges. Replay a duplicate update and introduce a corporate-action difference with an assigned reconciliation owner.
Bring the proposed broker, exchanges, instruments and reporting responsibilities to a scoped buyer discussion. Request a working replay and retained evidence for each exception; concept artwork cannot establish execution, settlement or lawful access.
Use our delivery process to agree acceptance records, correction authority and operations handover. Expand the product only after the selected client journey can be reconciled and supported through its unresolved states.
FAQ
It describes an independently branded brokerage workspace for selected lawful activities. The reference does not establish affiliation, exchange access, brokerage authorization or an available integration agreement.
An identifier can acknowledge an instruction without confirming execution. Inspect authoritative order status and individual trade records before recording a completed purchase or its account consequences.
Show its source and freshness, then apply the agreed submission policy. Revalidate current instrument and broker rules rather than promising execution at an old displayed price.
Preserve the attempted instruction and explain the current rejection reason. Do not silently change quantity, product or permissions to force acceptance through a different route.
Completed fills remain completed when cancellation affects the remainder. Preserve execution quantities and the final venue response, including fills that arrive while the cancellation is pending.
Trading activity and account inventory represent different records. Explain executed, unsettled and settled quantities using the selected broker and depository evidence without counting the same shares twice.
Margin and funds information can change with reservations, executions and broker decisions. Show its context and revalidate the actual instruction rather than guaranteeing acceptance from a screen value.
Connect reported executions, quantities, prices and finalized charges to authoritative records. Preserve delivery and correction history rather than treating the initial order confirmation as the complete client record.
Compare the relevant source and posting records, explain the pending difference and assign reconciliation ownership. Do not invent an entitlement or silently overwrite the earlier account history.
They require a separate reviewed product decision with applicable permissions, disclosures and risk controls. A cash-order workflow does not establish readiness for leverage, funding or liquidation.
The proposed scope presents account information and self-directed instructions. It promises neither investment advice nor returns; any advisory or research service needs separate authorized review.
Use fictional accounts to demonstrate stale data, rejection, partial execution and a cancellation race. Inspect positions, settlement, charges and corrections with traceable records and assigned exception owners.
Solution reference register
01 / Reference and IP
This page references third-party product names only to describe familiar product models and planning references. App Clone Labs is not affiliated with or endorsed by those brands. Build decisions require independent legal, regulatory, and operational review for your market.
02 / Regulatory caveat
Confirm licensing and market-specific authorization before enabling regulated activity · Define whether assets or funds are held by the operator, a qualified custodian, or not held at all · Apply security review, strong authentication, encryption, audit logging, recovery, and incident response · Present educational product information only and prohibit personalized financial, legal, tax, or wagering advice · Apply investor eligibility, disclosures, market-abuse surveillance, best-execution review, and complete books and records · Keep education separate from recommendations and require authorized review for any advisory or research service
Primary sources
Dated official documentation, standards, and research that support the factual claims on this page.
How to read this page
Scope, cost and timeline figures are planning guidance until confirmed in a written proposal. Diagrams and screens are illustrations, not client deliverables, and source-code rights and handover follow the signed agreement. See the delivery process and the full disclaimer.
Next decision
Define outcomes, constraints, evidence, rights and handover before delivery begins.
Commercial rights, repositories, environments, documentation, acceptance and handover remain contract-defined.
App Clone Labs is not affiliated with, sponsored by, or endorsed by Zerodha. The name identifies a familiar product category; every delivered product is independently designed and built, and the mark remains its owner's property. Read the full legal notice.
