A trading interface is not a brokerage authorisation
A white-label trading platform can provide a branded client interface and operational workspace around contracted account, market-data, execution, and reporting services. The important procurement question is which responsibilities belong to the operator, broker, custodian, clearing provider, and software team. An interface with prices and a buy button does not confer permissions to offer investments, hold assets, provide advice, or execute client orders. This is a reference engineering brief, not an investment recommendation or a claim of a live financial service.
Start with one intended market, an identified authorised operating model, and a bounded set of instruments and order types. Qualified advisers should determine the applicable promotion, account eligibility, suitability or appropriateness, recordkeeping, and other requirements. Software then implements the agreed controls. Do not assume that a partner API, a completed identity check, or a branded mobile app makes every instrument available to every client.
Define where the authoritative position lives
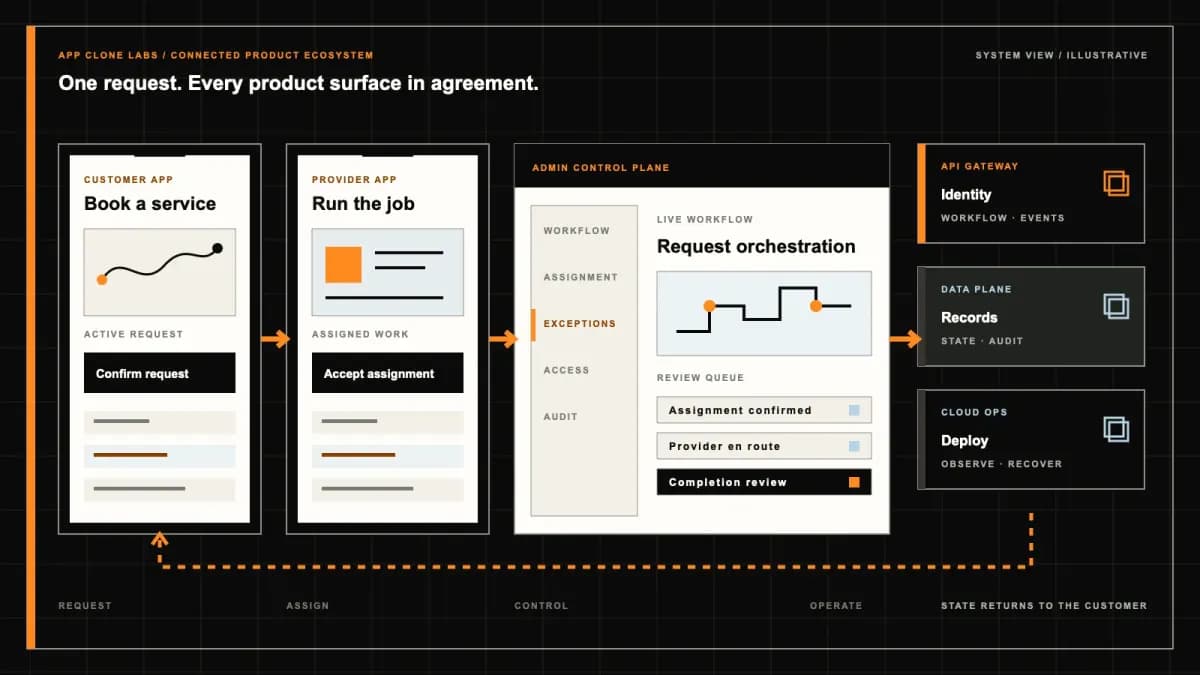
A broker-backed interface and an operator maintaining its own trading book are different systems. Identify the authority for open orders, executions, cash, holdings, fees, and statements. If the platform maintains derived views, document their update delay and reconciliation process. When records disagree, the product needs a visible pending or exception state rather than an automatic correction that conceals an unresolved financial difference.
The reference preferences screen illustrates settings such as alerts and broker selection. Sample prices do not demonstrate a licensed feed or an execution connection. Ask to inspect an order’s provider identifier, acknowledgement, fills, correction events, and reconciliation evidence. A walkthrough should distinguish simulated records from connected integrations. Provider access, entitlements, account approval, supported instruments, and security behaviour require separate verification.
Quotes, instructions, and executions are different records
A displayed quote is not a promise that an order will execute at that price. Preserve its instrument, source, timestamp, delay label, and market state. Define behaviour for a stale feed, closed session, halt, or unavailable instrument. A client should understand whether they are seeing an indicative value, delayed information, or a permitted actionable quote before submitting an instruction.
An instruction records account, instrument, side, quantity, order type, price conditions, duration, and the confirmation shown to the client. Validation must occur against the applicable account permissions and available buying capacity, not only form fields. Keep the original instruction version after submission. Later account settings or changed display precision must not rewrite the transaction that operations may need to investigate.
Design for partial fills and cancellation races
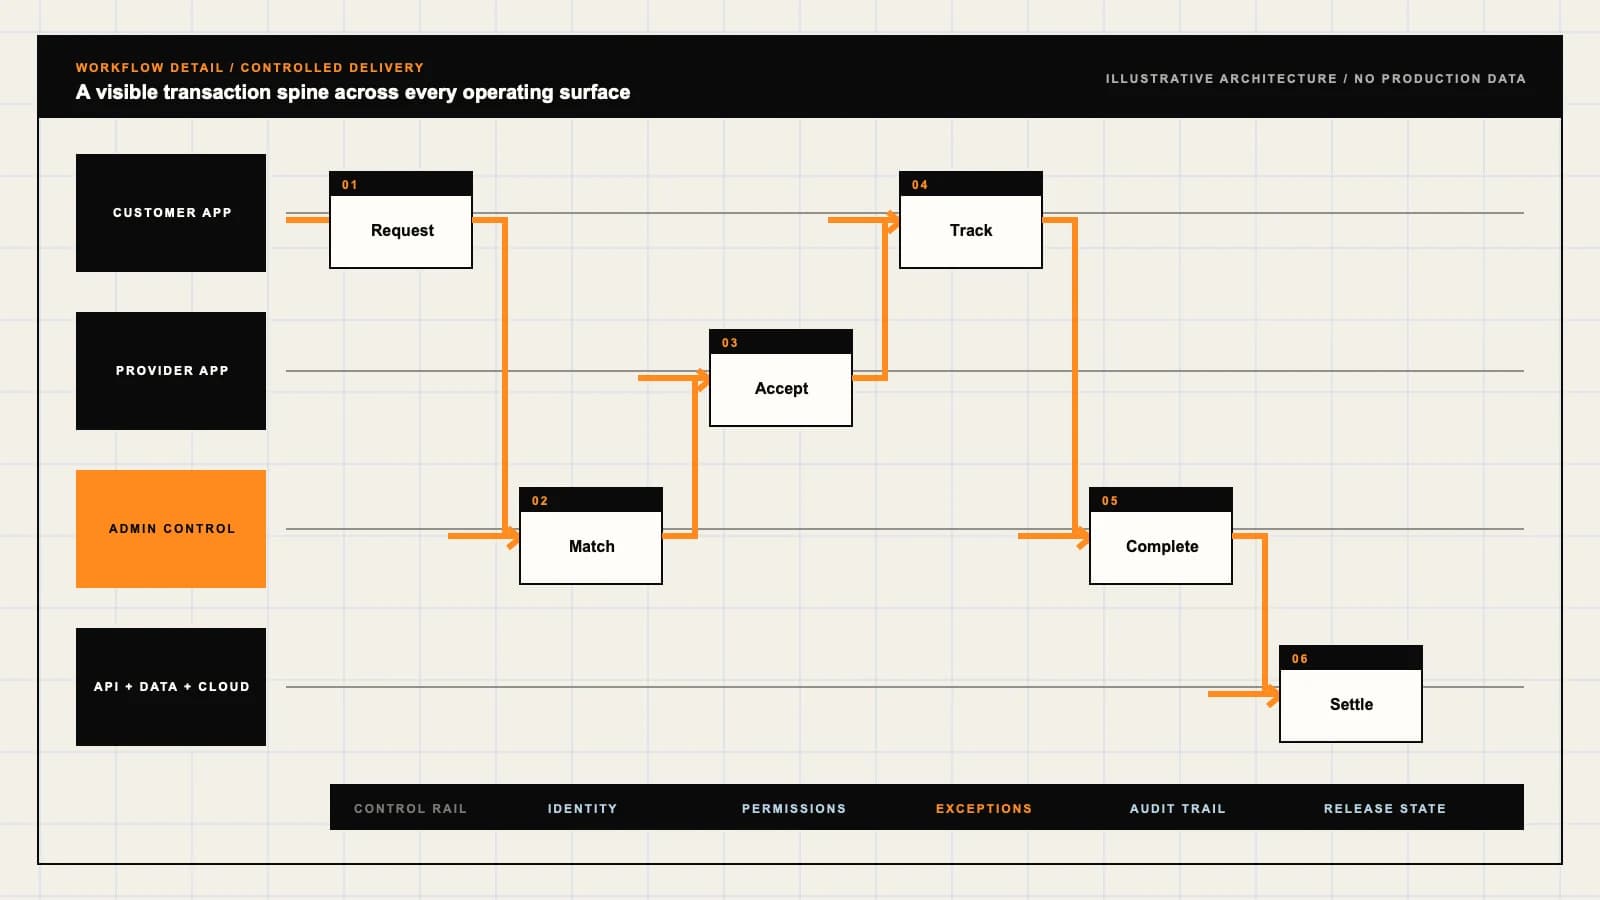
An order submitted to a provider may be acknowledged, rejected, partially filled, completed, expired, or still uncertain. Keep these states separate. A cancel request is not confirmation that an order was cancelled: a fill may arrive while cancellation is being processed. Show the confirmed outcome and retain both event histories. Do not label an order cancelled simply because the client tapped the button or the local request returned successfully.
Repeated messages and out-of-order events are normal recovery concerns. Correlate provider and platform identifiers and prevent another execution record from being created for an already processed event. After a disconnect, recover the provider state before allowing an ambiguous instruction to be resubmitted. Staff need an exception queue with permitted actions and evidence; they should not patch a position directly to make an account appear balanced.
Reconciliation extends beyond the trade screen
Compare executions, fees, cash movements, positions, and settlement records using the agreed authoritative sources. A filled order is not necessarily a settled cash movement. Corporate actions, instrument identifier changes, failed transfers, and corrections need their own event handling and review. Separate calculated views from official statements and explain unresolved items to authorised staff without leaking another account’s information.
Reconciliation should retain the inputs used, differences found, responsible reviewer, approved adjustments, and completion evidence. Restrict manual financial interventions and preserve reasons. Customer reports should not present indicative portfolio values as guaranteed realisable proceeds. Historical performance, projected returns, and any research functions require their own content policy and specialist review; they are not automatically included because a template has space for a chart.
For United States FINRA member firms, Rule 4511 on books and records is a primary recordkeeping reference. The relevant firm must establish the applicable record categories, retention, and storage requirements. A database history table alone is not a claim of regulatory compliance.
FINRA’s customer order-handling notice provides a United States member-firm reference for order handling during difficult market conditions. It supports reviewing operational responsibilities, not promising execution quality from this software brief or applying United States rules universally.